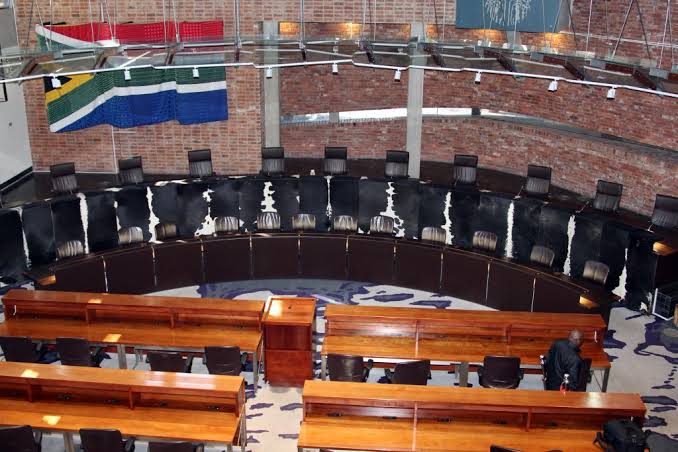
JOHANNESBURG, Thursday 27 August 2026 — The Constitutional Court has heard arguments over whether South Africa’s finance minister may change the VAT rate through a budget announcement before Parliament approves the adjustment, in a case that could permanently alter how one of the country’s most important taxes is set.
The Democratic Alliance is asking the court to confirm a March judgment of the Western Cape High Court declaring section 7(4) of the Value-Added Tax Act unconstitutional and invalid.
That provision permits the finance minister to announce a change in the VAT rate during the annual national budget and have the new rate take effect from a date specified in the announcement, before the adjustment is subsequently dealt with through legislation.
The High Court found that the provision amounted to an impermissible delegation of Parliament’s legislative taxing authority to the executive.
It suspended its declaration of invalidity for 24 months to give Parliament an opportunity to correct the legislation and referred the order to the Constitutional Court for confirmation, as required when a court declares legislation unconstitutional.
The dispute has its origins in Finance Minister Enoch Godongwana’s controversial 2025 budget proposal to increase VAT.
Godongwana initially proposed increasing the rate from 15% to 15.5%, followed by a further increase that would have taken it to 16%.
The proposal triggered opposition within Parliament and legal challenges from the DA and Economic Freedom Fighters.
The government ultimately withdrew the planned increase and VAT remained at 15%, but litigation continued over the constitutional question of whether a finance minister should possess the underlying power to alter the rate.
Arguing before the Constitutional Court on Thursday, DA counsel Ngwako Maenetje said the power to tax belongs to the legislature and cannot constitutionally be delegated to a member of the executive.
Maenetje argued that taxation is one of the state’s most intrusive powers because it determines how much money government takes from individuals and businesses, making parliamentary control fundamental to representative democracy.
DA parliamentary leader George Michalakis said outside the court that allowing the minister to determine VAT unilaterally could expose households to substantial tax increases without prior parliamentary approval.
The finance minister is opposing confirmation of the High Court order.
Advocate Kameshni Pillay, representing Godongwana, argued that section 7(4) serves an important fiscal-management function by allowing government to respond quickly to revenue shortfalls or other immediate pressures.
She argued that the mechanism does not ultimately displace Parliament’s taxing authority because legislative approval remains part of the process.
The dispute therefore turns on a broader constitutional question: whether Parliament may delegate temporary authority over a tax rate to the executive when Parliament retains the power to legislate afterwards.
The High Court concluded that the existing mechanism went too far.
Its March judgment emphasised that section 7(4) contains no express statutory limit on the size of an adjustment the minister may announce and does not require Parliament to ratify the change within a short prescribed period.
The court also found that VAT is collected transaction by transaction, meaning tax collected under a ministerially announced rate cannot simply be undone if Parliament subsequently declines to approve the adjustment.
The Constitutional Court’s eventual ruling could consequently have implications beyond the abandoned 2025 VAT increase.
A confirmation of invalidity would require Parliament to rewrite the VAT Act and establish a constitutionally compliant mechanism for future rate changes.
It could also clarify the limits of Parliament’s ability to delegate taxation powers to the executive, potentially influencing future disputes involving other taxes and levies.
The case also has political significance because the original VAT dispute became one of the most serious disagreements over economic policy after the formation of the Government of National Unity.
The DA opposed the proposed increase while participating in the GNU, demonstrating the extent to which coalition partners could challenge fiscal decisions taken by an ANC-led executive.
Parliament subsequently entered an out-of-court settlement in April 2025 that suspended the proposed VAT increase and set aside resolutions approving the original fiscal framework, allowing a revised budget to be introduced.
The current proceedings are narrower: they concern the constitutionality of the statutory power itself rather than whether VAT should be increased.
The Constitutional Court heard competing arguments on Thursday over the balance between rapid fiscal decision-making and Parliament’s constitutional authority over taxation.
Its final order will determine whether the High Court’s declaration of invalidity stands and, if it does, leave Parliament with responsibility for replacing section 7(4) with a new mechanism governing future VAT-rate changes.